Wage Reporting: Need to Know
Collection Actions
Employers are required to make payment in full for all assessments of contributions , surcharges and / or reimbursements on or before the due date provided in statute.
Employers who have elected to become reimbursable are required to reimburse the Department of Workforce Development when benefit charges are paid to a claimant. A contributory employer pays unemployment taxes quarterly regardless of whether a claimant receives unemployment benefits.
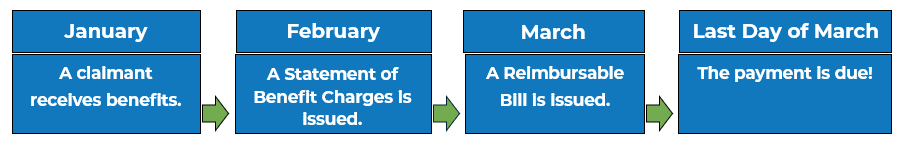
Both contributory and reimbursable employers will receive a Statement of Benefit Charges which identifies the individuals who received unemployment benefits for the month identified on the statement.
Approximately 30 days after the issuance of the Statement of Benefit Charges, a Reimbursable employer will receive a Reimbursable Bill. Reimbursable Bills are issued monthly when an account has an amount due. The Reimbursable Bill is due on the last day of the month for which the bill was issued.
The due date for contributory employers is the last day of the month following the end of the quarter. As an example, the first quarter of a year consists of January, February and March. The first quarter report and any associated payment is due by the last day of April. Please see the section titled Quarterly Report Due Dates for a chart of contributory due dates.
|
If an employer fails to make the required full payment timely, the employer will be subject to various punitive measures such as interest, penalties, fines, fees, damages, and court costs.
|
If a reimbursable employer chooses to dispute the benefit charges paid to a claimant, a written protest must be submitted. The written protest must be submitted within fifteen (15) days from the date of the Statement of Benefit Charges and not from the date of the Reimbursable Bill. It is important to note that a reimbursing employer must reimburse the Department whenever benefit charges are paid to a claimant. This is the case even if a written protest is received and regardless of whether a claimant is later determined to be ineligible to have received the benefits. The employer protest form, SF55109, can be found here.
Please be aware that DWD has the presumption of being correct when issuing a Reimbursable Bill, so the accrual of interest is not stopped by a protest. The employer should also be aware that part of the election to be reimbursable is a certification that the employer will make payment in full as billed.
Contributory employers receive a notice of assessment known as a Notice and Demand only when unpaid contribution and/or unpaid interest and/or unpaid penalty are established for a quarter. In addition to any other notices regarding an assessment, DWD will issue a Notice and Demand to a contributory employer. Employers should respond promptly to the Notice and Demand by either filing a written protest, remitting payment in full or establishing a payment agreement. Contributory employers have fifteen (15) days from the date of the Notice and Demand, to protest the assessment in writing. The employer protest form, SF55109, can be found here .
As with a Reimbursable Bill, DWD is considered to have correctly assessed the contributory employer at the time the assessment is made, and a Notice and Demand is issued.
|
DWD will not initiate collection action against an employer while the assessment is under protest, but the protest does not stop the accrual of interest on the contribution or benefit charge amount due.
|
Employers are strongly encouraged to pay all amounts assessed even if they are protesting to keep interest from continuing to accrue. If the employer wins the protest, they can receive a refund of any payment where DWD has wrongfully assessed the amount due if the request for refund is received timely.
If the employer has not protested the assessment, submitted payment in full or entered into a repayment agreement, DWD has legal authority to take aggressive collection action.
DWD can file a tax lien with the clerk of the county court against the business, a person and the property of the business including the responsible parties as described in the section titled Terminating a Business. If the Department files a tax lien, additional fees and costs will be assessed against the business, a person and the property of the business.
DWD can request that the sheriff serve a tax warrant on a business and the responsible parties which can include such actions by the sheriff as a bank levy or seizure of the business assets for sale at auction. DWD can file a request with the Attorney General to enjoin a business against operating in Indiana. DWD can levy the bank account and / or the accounts receivable of the business.
DWD can intercept any tax returns of the business as well as the responsible parties as described in the section titled Terminating a Business.
If the Department takes any of the enforcement actions authorized by statute to collect the outstanding liability due to the Department, additional fees may be assessed.
Employers can avoid collection enforcement action by filing all required returns and remitting payment in a timely manner, communicating changes in the filing status of the business promptly to DWD, and responding to all mailings from DWD in writing.
If your business experiences a cash flow problem or needs additional time to make payment in full on a quarterly return or a reimbursable bill, payment agreements are available if certain conditions are met. Please contact the DWD Collection and Enforcement Unit, at 800-891-6499 (option 2 for employers) to learn more about payment agreements before DWD is forced to take collection action against you and your business.
Wage Garnishments
If you have questions regarding wage garnishments, please email: AskUI@dwd.in.gov or Call, 800-262-6949.